Before paying a deposit for a used production line, establish exactly what is being sold, who is entitled to sell it and how it can be handed over and put into operation. The quoted price becomes useful once those conditions and the cost of commissioning are understood.
This article concerns a direct purchase of individual machines from a company in Türkiye. Buying company shares, buying at a judicial auction and purchasing through insolvency proceedings require separate checks. If the equipment will leave Türkiye, check destination-country customs and technical requirements before committing to buy.
Identify the equipment first
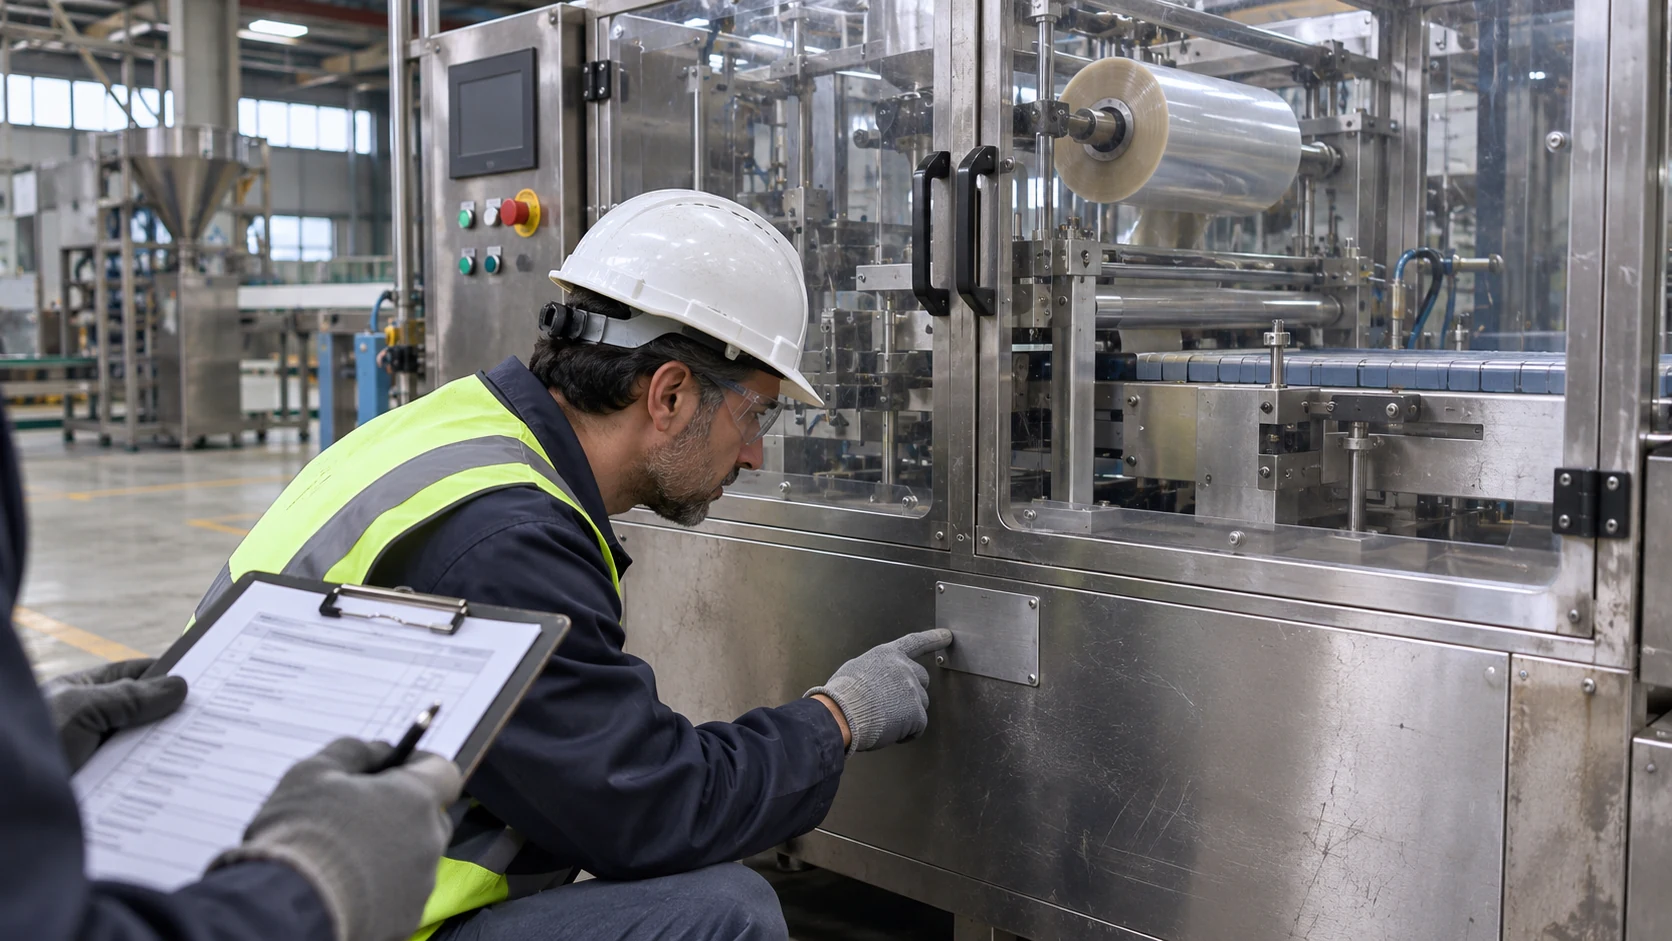
Prepare a contract schedule listing the manufacturer, model, serial numbers, year, included components and inspection location. Match it against the machine plates and the seller’s documents. For a line, list modules, tooling, control cabinets, spare parts, manuals and software separately. Establish which licences and access rights can be transferred.
“In working condition” leaves too much open. A payment decision needs an agreed scope and test criteria: input material, speed, finished-product quality, permitted deviations and measurement conditions. Use a technical specialist who can assess whether the machine suits your intended production.
Establish the seller’s authority
Request acquisition and asset records, company details and current evidence of the signatory’s authority. Establish whether the seller owns the equipment. If an intermediary is involved, clarify whose behalf it acts on and its authority to receive payment. The machine’s presence on the factory floor does not establish these points.
Ask separately about finance leases, rental arrangements, pledges and other third-party rights. Read the documents together: an invoice or accounting entry does not replace legal review of the ownership chain. If the seller is subject to debt restructuring, insolvency or enforcement proceedings, have Turkish counsel check its authority to make this particular sale and any approvals required before payment.
Check TARES and the scope of the search
Law No. 6750 on movable pledges in commercial transactions permits machinery and equipment to be pledged without delivery to the creditor. Articles 4, 8 and 9 connect the creation of this pledge and its effect against third parties with registration in the Movable Pledge Registry. The Ministry of Trade describes TARES as the system for that registry.
The scope of pledged assets matters. Under Article 5(2), a pledge can cover an entire enterprise or a defined group of movable assets. Searching only for an individual machine’s serial number should therefore not be treated as sufficient to check whether it falls within a group pledge.
Agree suitable search parameters and the relevant registries and documents with counsel. Retain the results, search date and scope. A search producing no TARES entry should not be treated as proof of ownership or absence of every restriction: registry coverage and legal regimes differ. Where a pledge exists, agree a verifiable release process or another permissible transfer arrangement with the seller and creditor before payment. The seller’s promise to settle its debt later does not establish that the asset will be transferred free of the pledge.
Case: the line is available, but handover remains unresolved
Suppose a company offers a used packaging line and requests a deposit to reserve it. Some modules operate during inspection, but a complete test has not taken place. The dismantling arrangements and information about encumbrances have yet to be provided.
The buyer can first list the missing evidence. If a test is only possible before dismantling, arrange it at the operating site. If a pledge is identified, review how it will be dealt with before paying the relevant part of the price. Until these conditions are settled, the advertised discount does not show the transaction’s full risk.
Link payment to verifiable stages
Agree which documents and actions precede each payment. The arrangement below is a starting point for negotiation, not a statutory schedule or a guarantee that money can be recovered.
| Stage | Evidence before payment |
|---|---|
| Reservation | Exact equipment scope, reservation period and terms for crediting or refunding the deposit |
| Review before dismantling | Legal documents, agreed test results and defect list |
| Handover and removal | Encumbrances addressed through the agreed process, completeness, handover documents and access for removal |
| Acceptance after installation | Agreed performance checks, recorded defects and outstanding obligations, where this stage forms part of the deal |
Define the consequences of a failed test, late documents, dismantling damage and inability to remove the equipment. Allocate packing, loading, transport, insurance, installation and retesting costs, and specify when risk passes. Assess a deposit-refund clause alongside the practical ability to recover money from the seller.
Budget for the machine in operation
Add repairs, missing tooling, software licences, dismantling and commissioning to the purchase price. Check transaction-specific taxes and documentation with the accountant. Have the technical team review power, connections, safety and servicing at the new site. Operation at the previous factory does not establish readiness for a different location and production task.
Before the deposit, assemble one transaction file: equipment identification, seller documents, legal and technical findings, open questions, budget and payment terms. Assign an owner and deadline to each unresolved item. Where an item determines whether the machine can be acquired or used, the payment decision needs to address it before money is sent.
Official sources
- Law No. 6750 on movable pledges in commercial transactions: Articles 4, 5, 8 and 9; published on 28 October 2016 in Official Gazette No. 29871, text as amended.
- Türkiye’s Ministry of Trade: movable pledges, TARES and the regime’s scope.
Reviewed on 10 November 2026. The document list and payment sequence are transaction-planning recommendations. The adequacy of checks and conditions for transfer depend on the particular assets and rights involved.